Most of the money went into data centres, offices and development land, not completed homes.
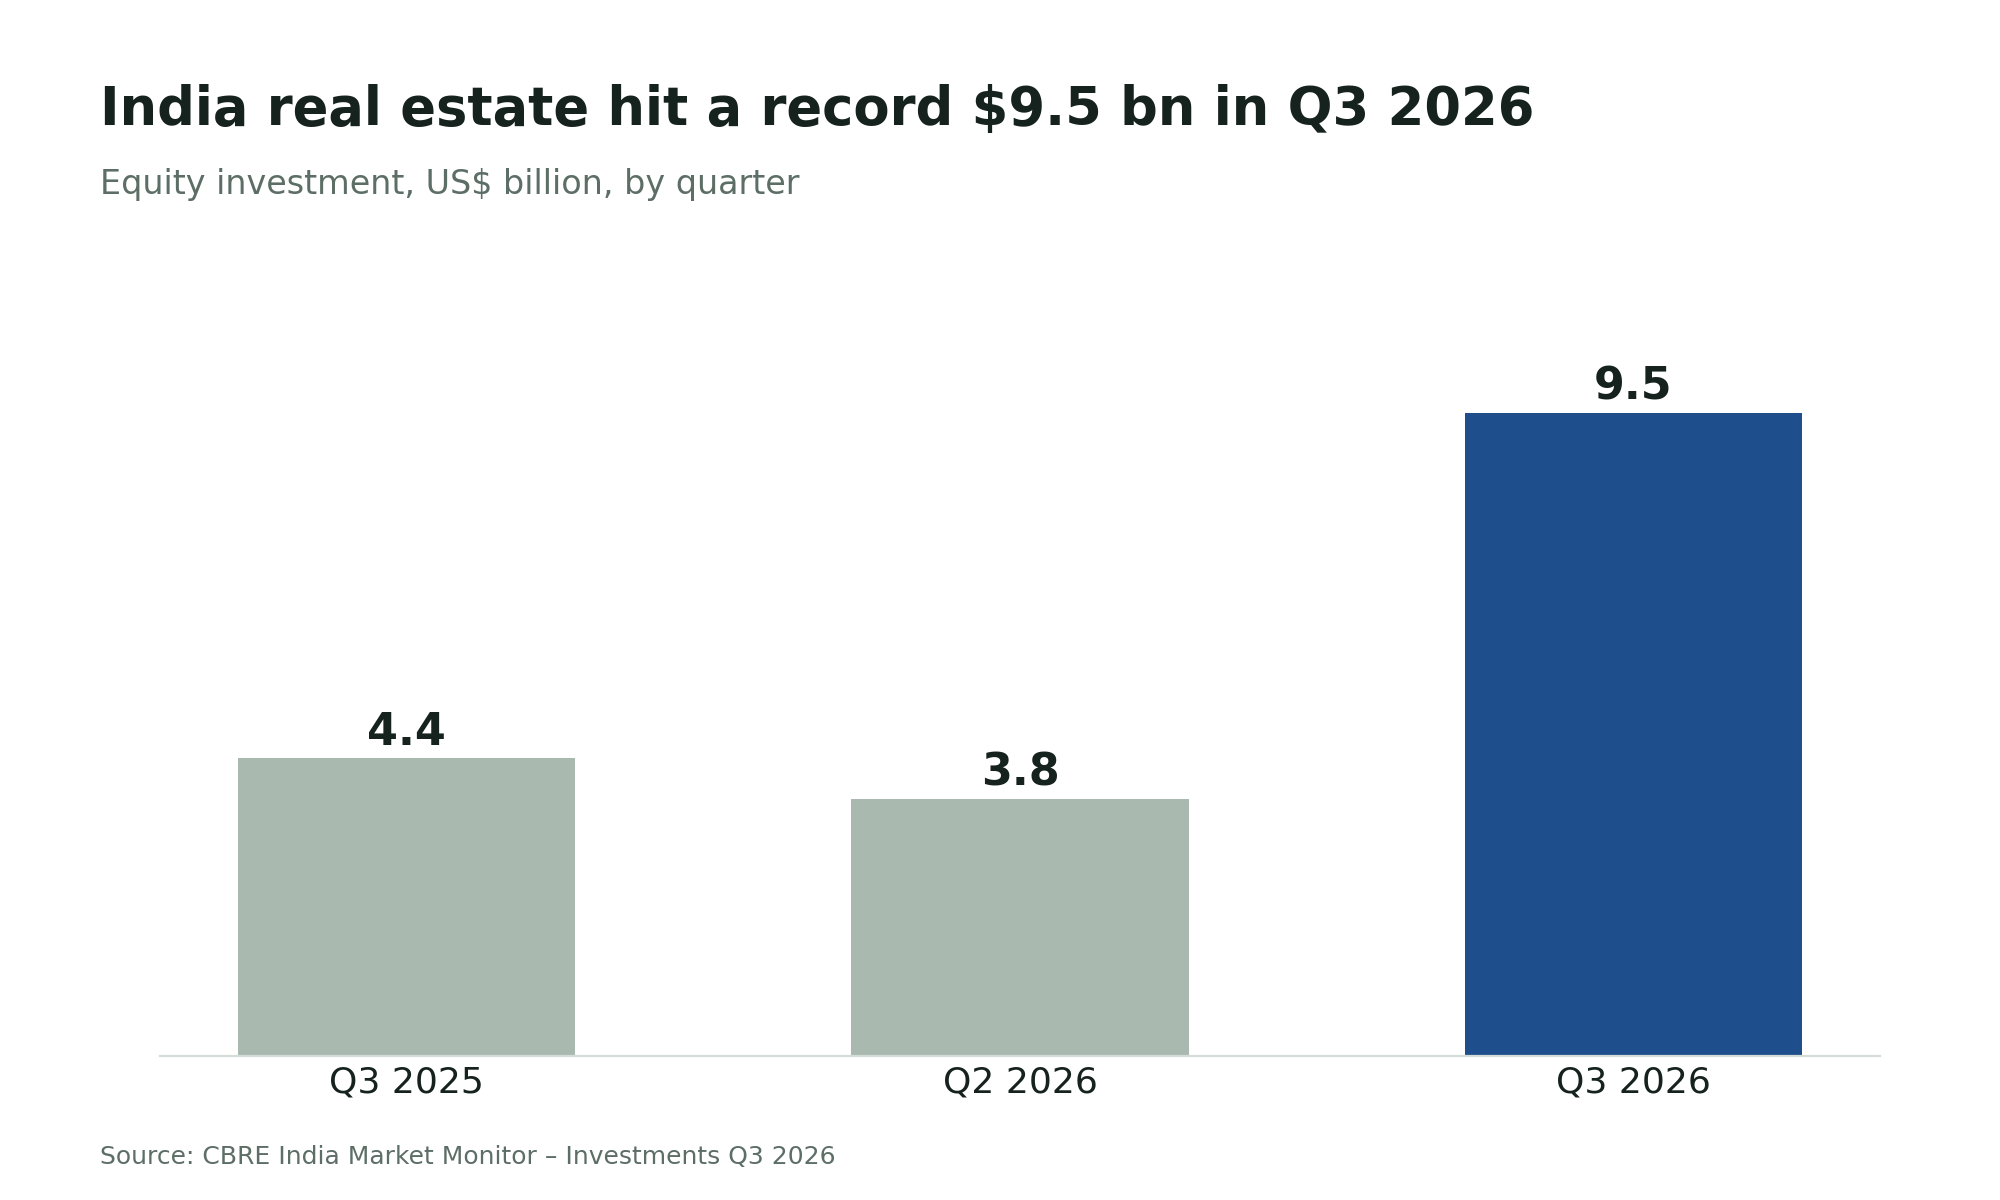
India's real estate sector took in $9.5 billion of equity capital between July and September 2026. CBRE says this is the highest quarterly figure it has recorded.
The number is more than double the $4.4 billion seen in the same quarter of 2025. It is also far above the $3.8 billion of Q2 2026.
Already ahead of last year
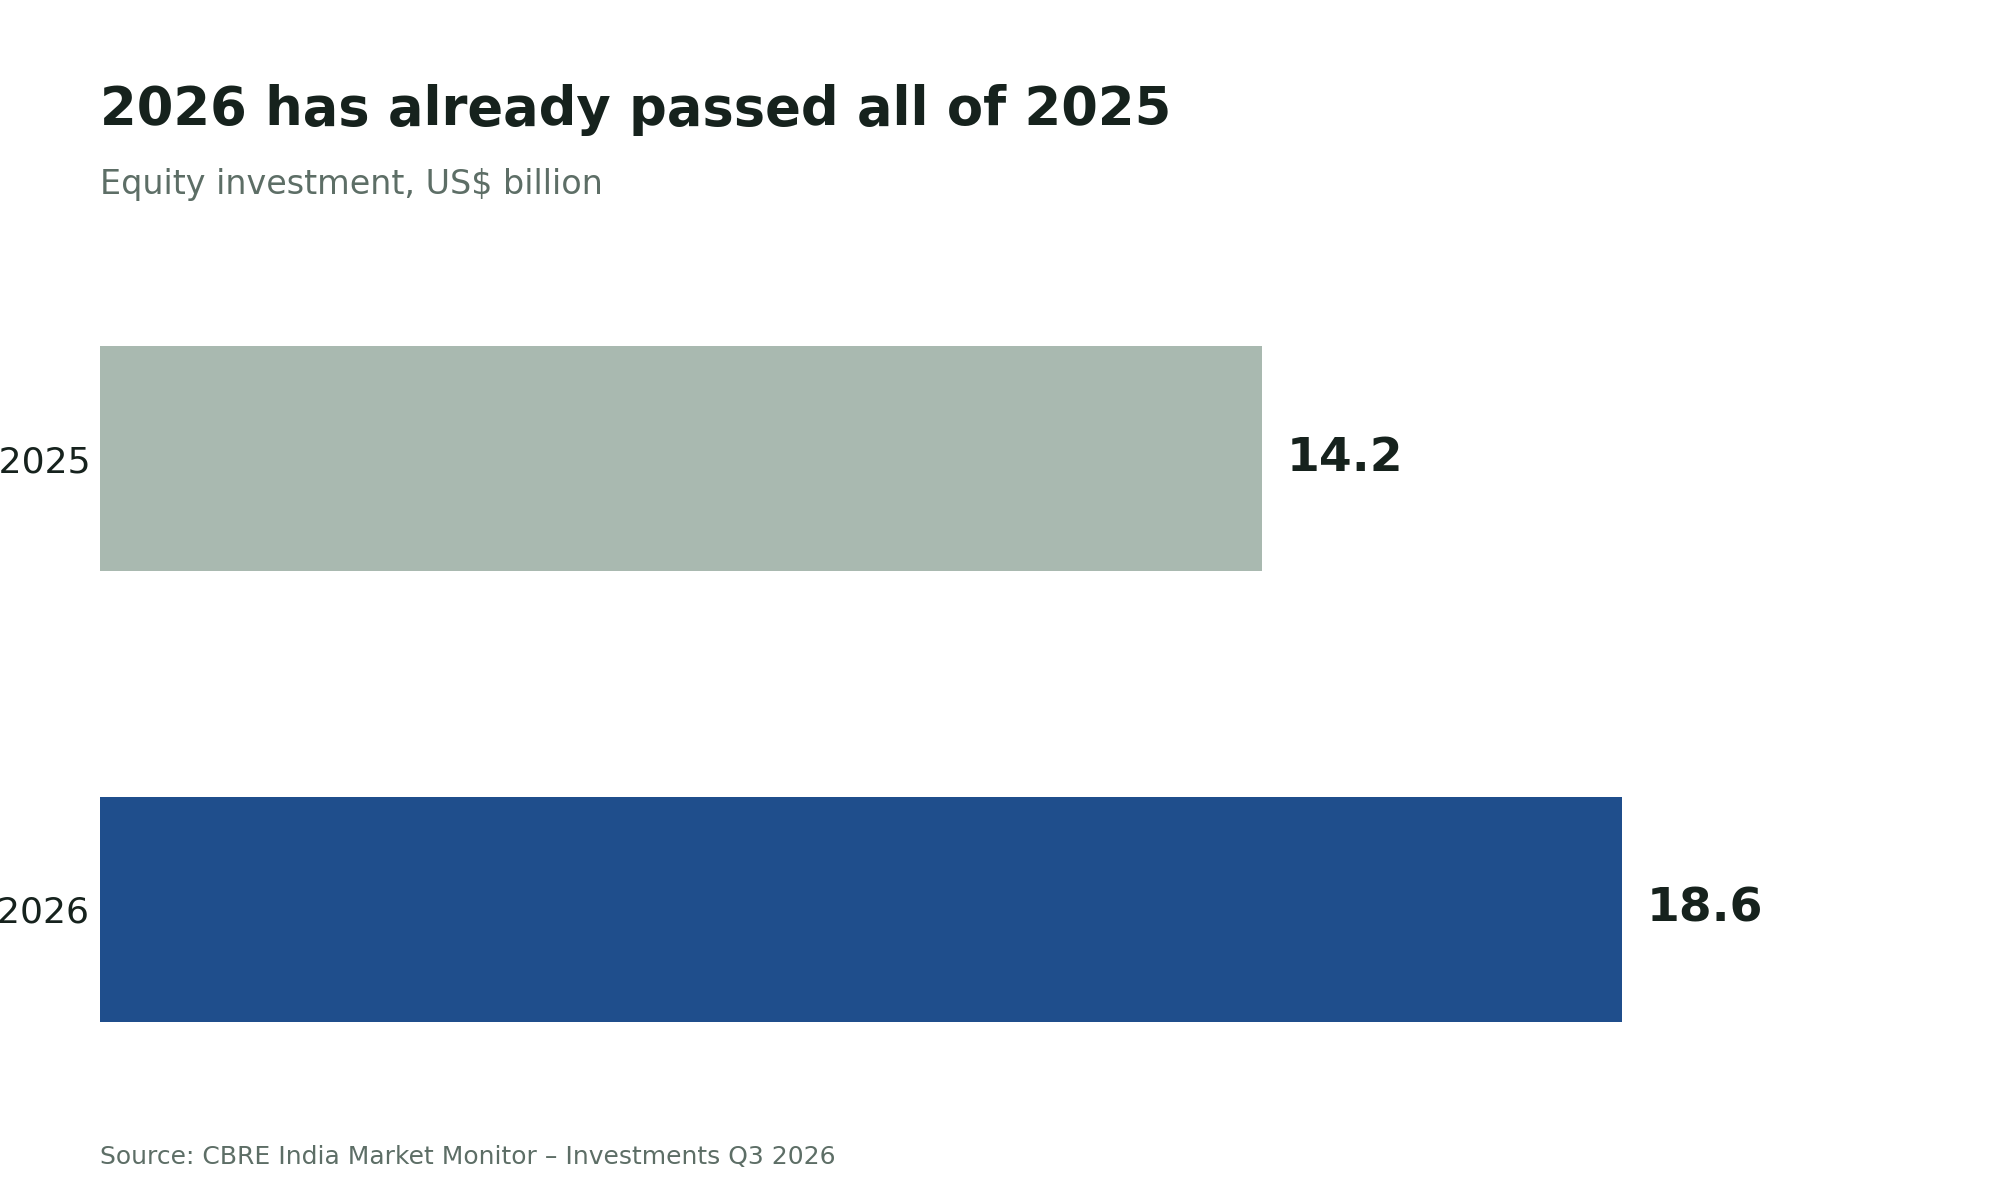
In the first nine months of 2026, the sector has drawn $18.6 billion. All of 2025 brought in $14.2 billion. So the year has passed last year's total with one quarter still left. Nine-month inflows are close to double the same period of 2025.
Where the money went
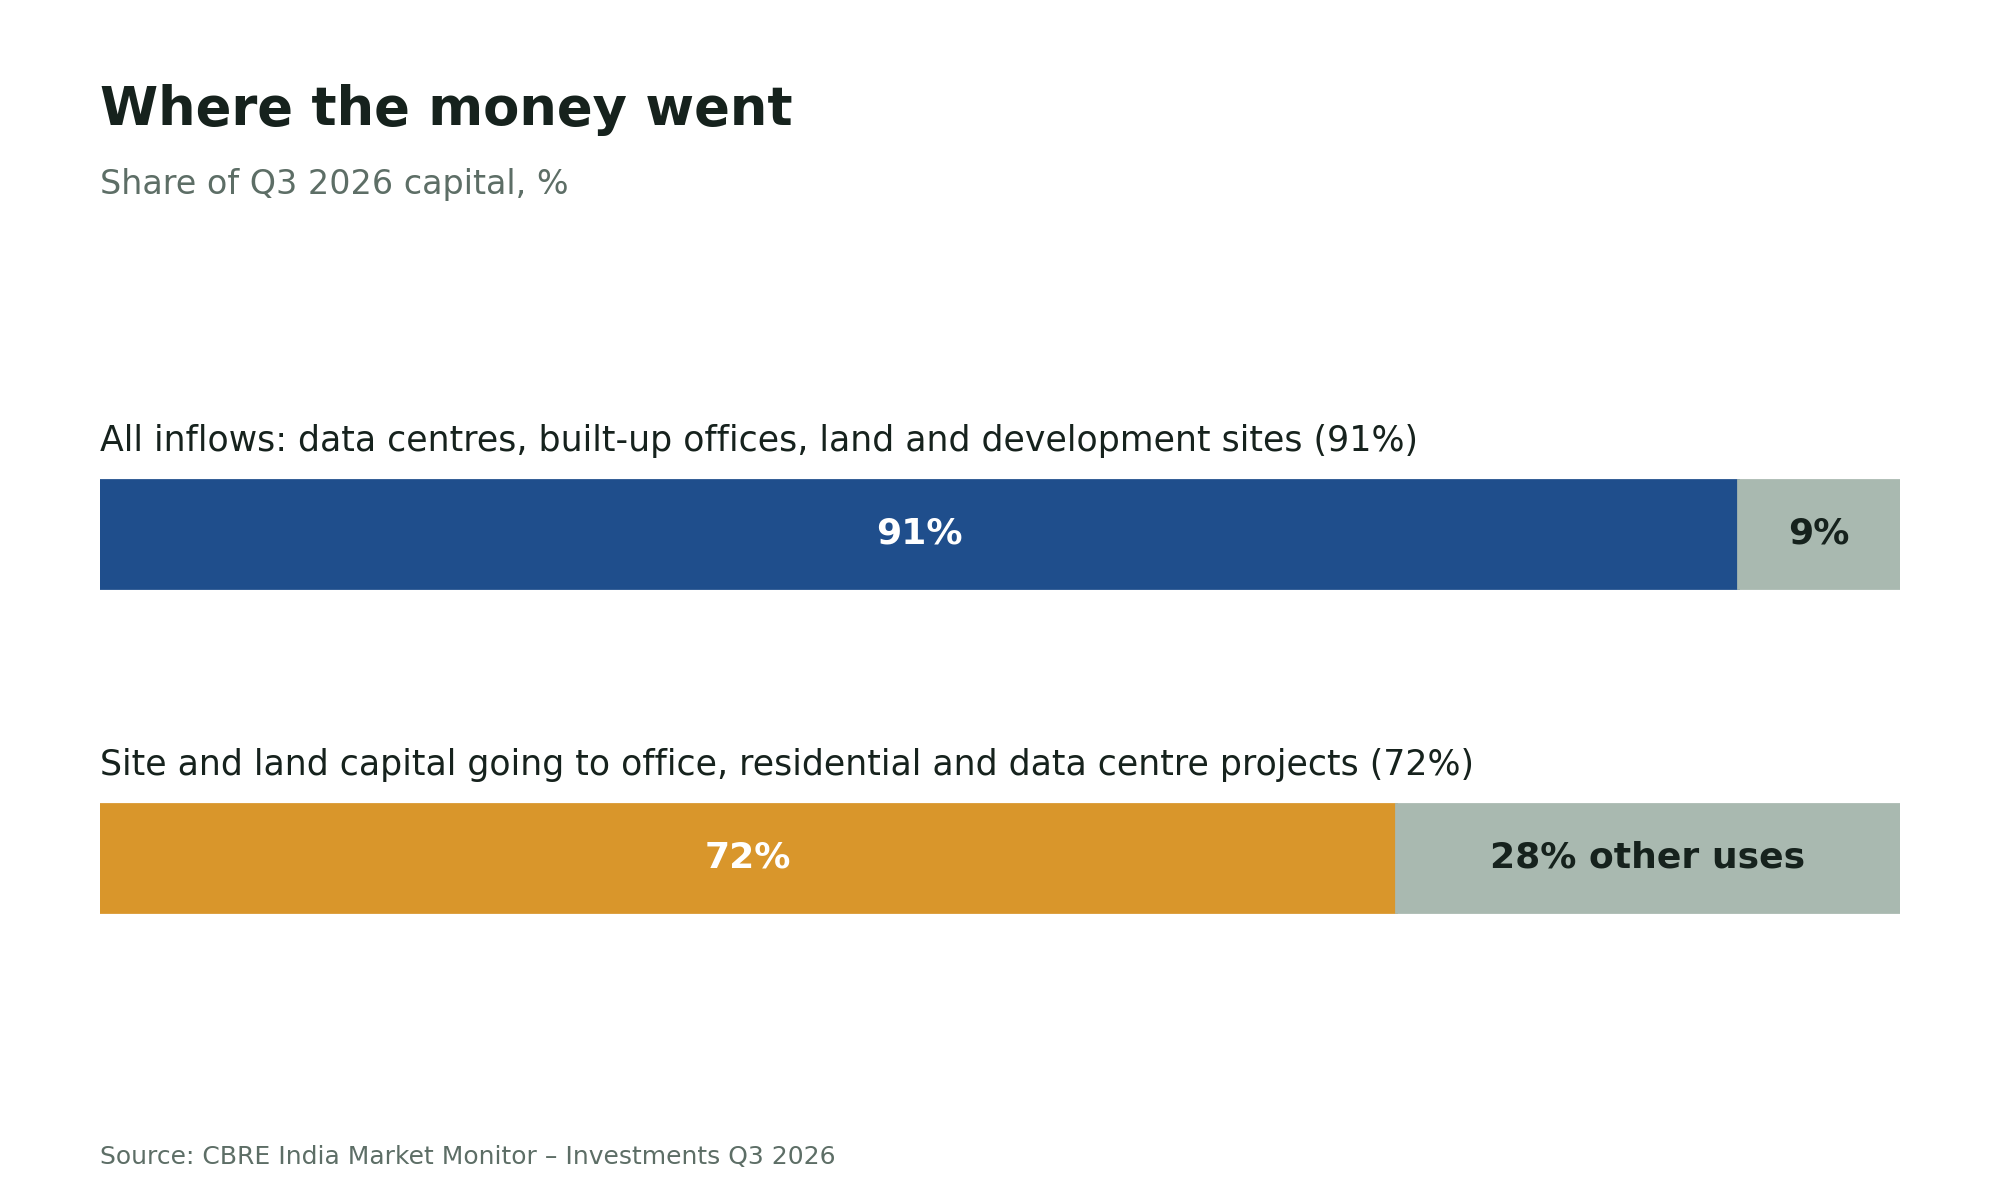
Three segments took nearly 91% of Q3 inflows: data centres, built-up offices, and land or development sites. Data centres grew several times over against both the previous quarter and a year ago. CBRE links this to digitalisation, AI-led demand and capital commitments.
Land deals tell a similar story. About 72% of the capital spent on site acquisitions went to office, residential and data centre projects. The rest went to mixed-use, hotel, retail, and industrial and logistics.
Who is investing
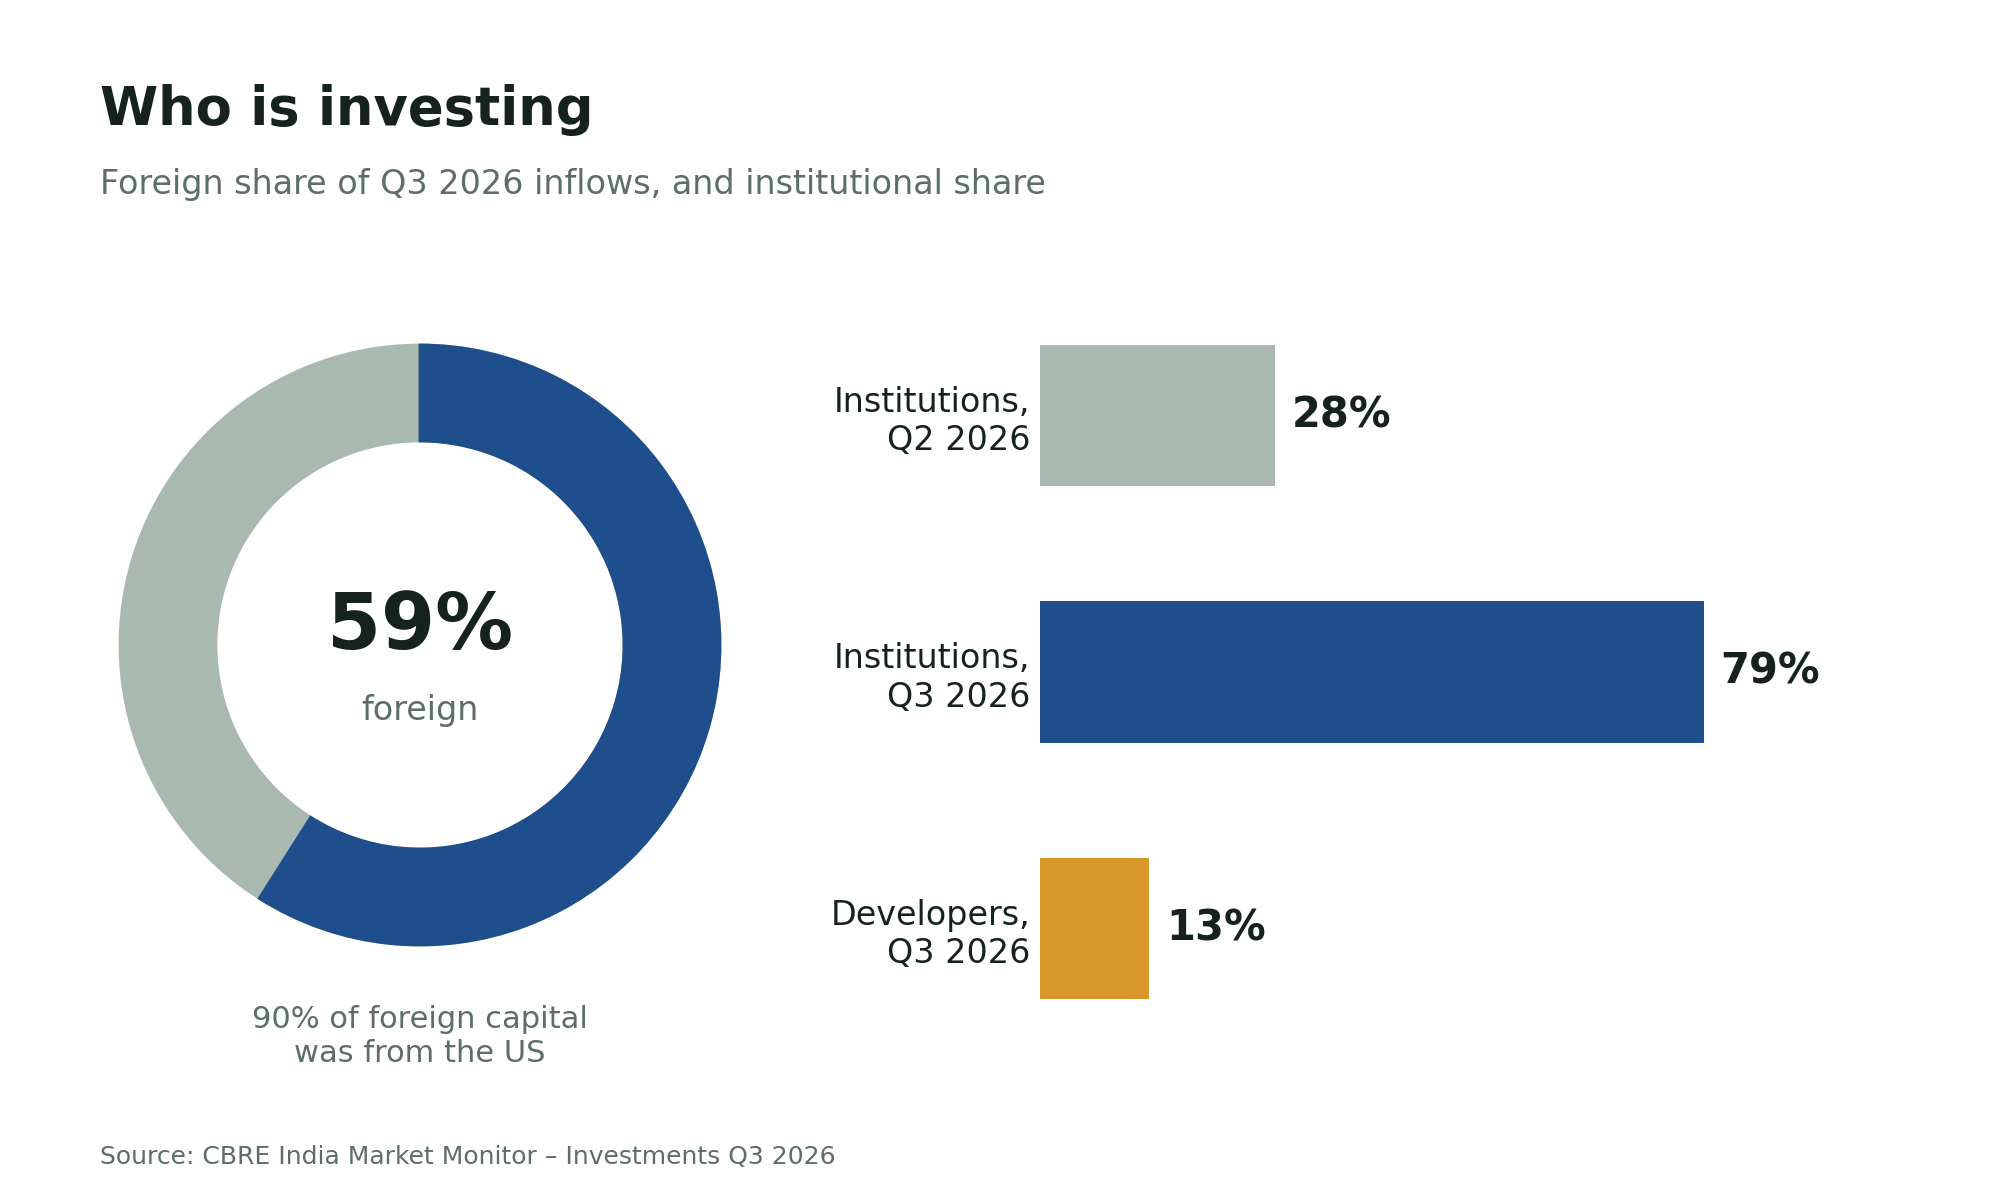
Foreign investors supplied about 59% of the total. US investors made up 90% of that foreign money. Canada, Singapore and Japan followed.
Institutions accounted for about 79% of all inflows, up from about 28% in the previous quarter. Developers had a share of about 13%.
Which cities
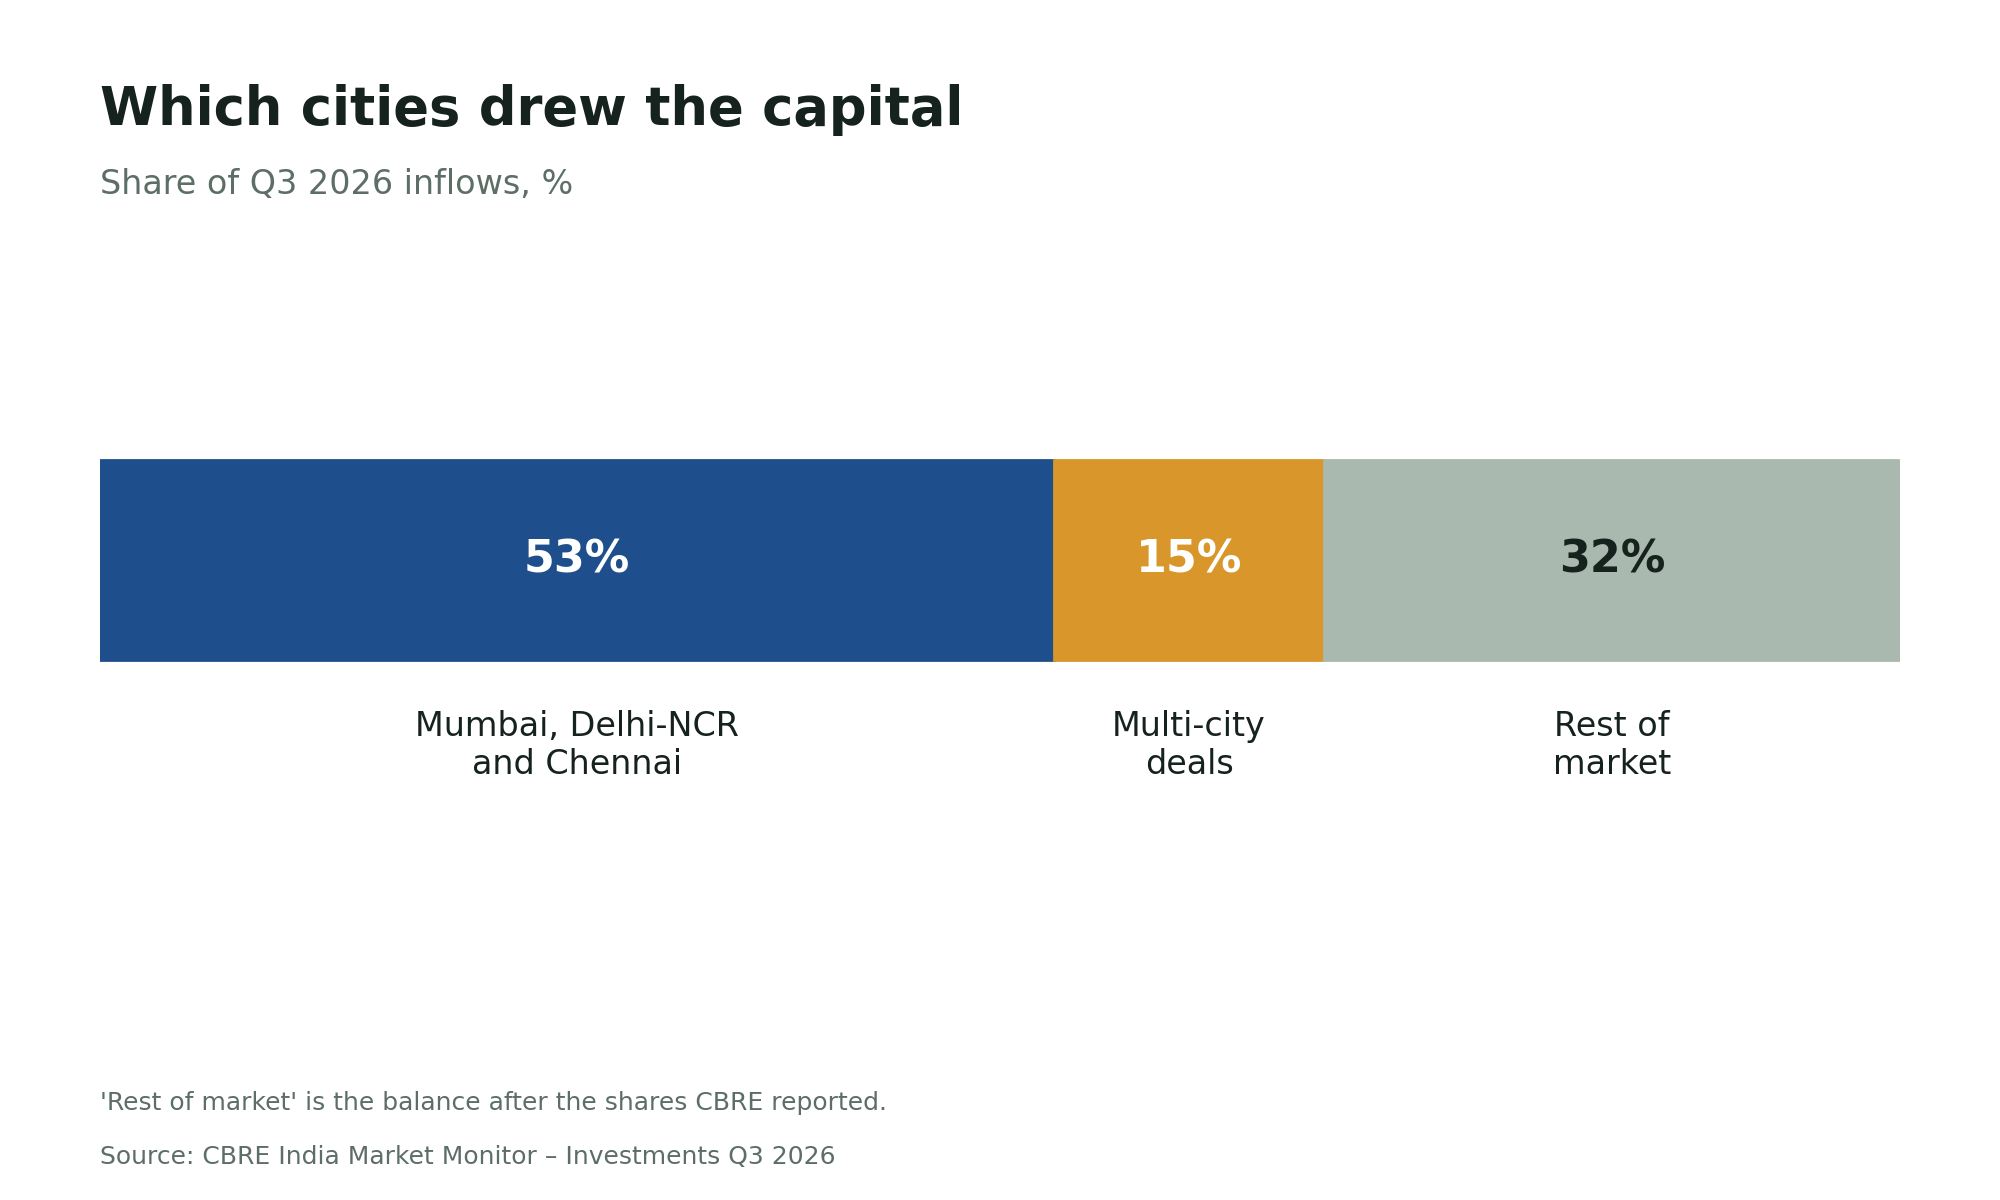
Mumbai, Delhi-NCR and Chennai together drew about 53% of the money. Deals spread across several cities added another 15%. Separately, investment and development platforms worth about $1.6 billion were set up across core and emerging segments.
What CBRE expects
Anshuman Magazine, CBRE's chairman and CEO for India, South-East Asia, Middle East and Africa, called it a landmark quarter. He said global investors have come back with conviction, and he expects that confidence to last through the year. Gaurav Kumar, managing director and co-head of capital markets in India, also expects the momentum to continue, backed by a mature and varied pool of capital.
For context, land and development sites made up over 46% of 2025 inflows, and built-up offices about 28%. This year the money is spread across more asset types.
The mix matters. Institutional interest is no longer limited to offices and land. It now covers income-generating built-up assets, infrastructure-linked assets and development sites.
Source: CBRE India Market Monitor – Investments Q3 2026